AGZIT-CIFS
Intermediate · Financial Crime

AGZIT Certified Investment Fraud Specialist

Awarded on completion of Certified Investment Fraud Specialist

Recognise when a customer is being defrauded of their own money, verify what they are being sold from sources the seller does not control, and act before the transfer leaves. One payment covers the course, the study guide and the certificate.
ONRIGA Accredited Globally Recognised Verifiable Certificate

What you earn

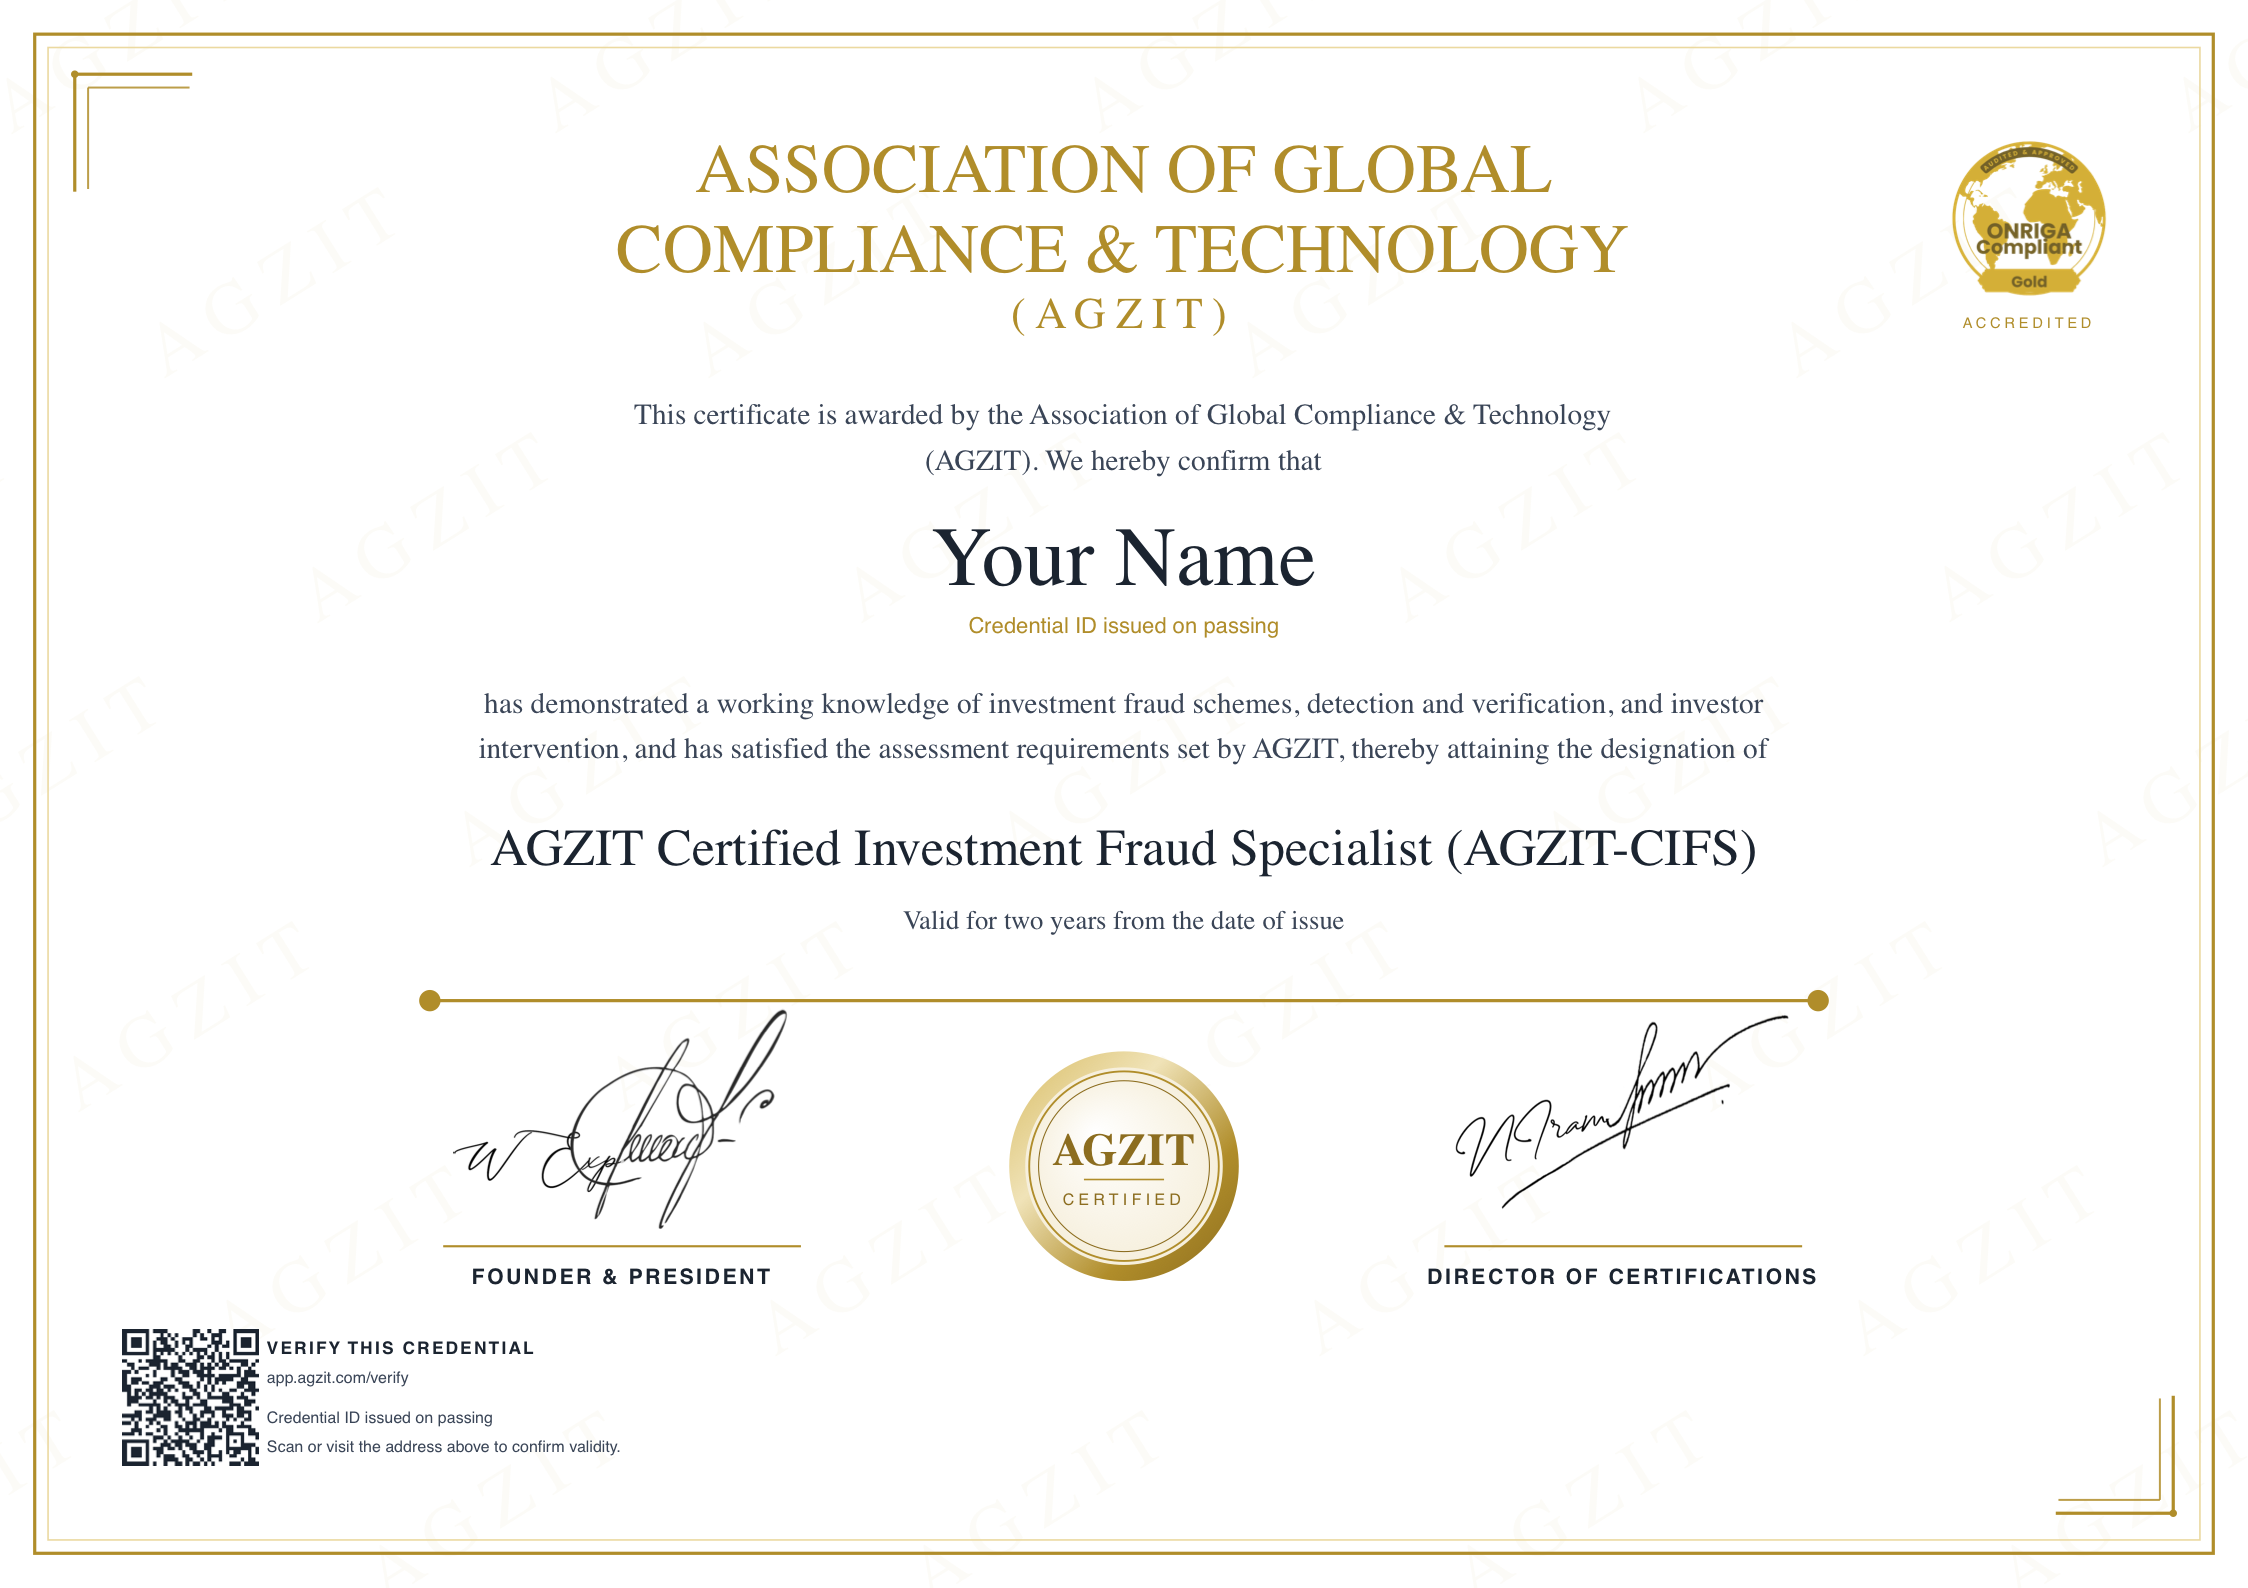
On passing the final assessment you are awarded the AGZIT Certified Investment Fraud Specialist (AGZIT-CIFS), issued with a credential ID anyone can check at app.agzit.com/verify.

Curriculum

  1. Study Material 1 module · 1 lesson with a downloadable ebook you keep
    • Study Material AGZIT-CIFS Study Guide
    Full syllabus, module by module
    Module 1 — The investor as the victim 1.1 Why protecting a customer differs from protecting a firm 1.2 Who the perpetrators are 1.3 How investment fraud differs from payments fraud 1.4 Why almost nothing works after the money moves 1.5 Where the specialist sits inside a firm Module 2 — Market and securities manipulation 2.1 Pump and dump 2.2 Microcap and penny stock fraud 2.3 Boiler room operations 2.4 Insider tips as bait 2.5 Churning and excessive trading 2.6 What a firm can and cannot stop Module 3 — Structural and relational fraud 3.1 Ponzi schemes 3.2 Pyramid schemes 3.3 Affinity fraud 3.4 Pig butchering and financial grooming 3.5 Recovery-room fraud 3.6 Why the same victim is approached twice Module 4 — Fee, access and entity deception 4.1 Advance fee fraud 4.2 Prime bank and secret trading programmes 4.3 Pre-IPO and private placement scams 4.4 High-yield investment programmes 4.5 Promissory note fraud 4.6 Financial statement fraud 4.7 Advisor impersonation and cloned firms 4.8 Alternative assets: crypto and real estate Module 5 — How the approach arrives 5.1 Cold contact: telephone, message and email 5.2 Social media, messaging and advertising 5.3 Social engineering and the trust script 5.4 Deepfakes and synthetic media 5.5 Testimonials, reviews and manufactured credibility 5.6 Urgency, exclusivity and the close Module 6 — The vulnerable investor 6.1 Who is vulnerable, and why 6.2 Diminished capacity 6.3 Undue influence 6.4 Family, caregiver and fiduciary abuse 6.5 Isolation as a method 6.6 Reading the account of a vulnerable customer 6.7 What a firm may and may not conclude Module 7 — Detection inside the account 7.1 What changes before money leaves 7.2 Transactional red flags 7.3 Behavioural and communication red flags 7.4 A bad decision is not a fraud 7.5 Alerting, surveillance and case selection 7.6 Building the timeline Module 8 — Verification 8.1 Registration and licensing checks 8.2 Verifying an entity 8.3 Verifying a person 8.4 Verifying the offer and its documents 8.5 Sources the subject does not control 8.6 Cannot be verified as a finding Module 9 — Intervention under United States rules 9.1 The regime, and how to find your own 9.2 Trusted contacts 9.3 Temporary holds 9.4 The clock on each intervention 9.5 What is available without a rule 9.6 Raising it with the customer 9.7 Acting in the hours after a loss Module 10 — The case file and reporting 10.1 Evidence, and how fast it disappears 10.2 Writing a file that survives 10.3 Writing the suspicious activity narrative 10.4 Where else a report goes 10.5 Closing a case 10.6 When the file is challenged Module 11 — Conduct and boundaries 11.1 What a specialist may represent and claim 11.2 Not investment advice, not a suitability assessment 11.3 Not a clinical assessment, and not an investigator 11.4 Why nobody can promise recovery 11.5 Privacy, disclosure and the limits of what may be said 11.6 Being wrong, and keeping going
  2. Practice Assessment A rehearsal under the same clock — your result here does not affect your certificate.
    100 questions90 min70% to pass2 attempts
  3. Final Assessment Passing this awards the certificate.
    100 questions90 min70% to pass2 attempts

How the assessment works

Questions are drawn from a larger bank, so attempts differ.

No webcam or microphone is required, and there is no proctoring. Sit it online from anywhere, at any time — you need a stable connection and a laptop or desktop, which the timed navigation is built for.

Syllabus

Module 1 — The investor as the victim
1.1 Why protecting a customer differs from protecting a firm
1.2 Who the perpetrators are
1.3 How investment fraud differs from payments fraud
1.4 Why almost nothing works after the money moves
1.5 Where the specialist sits inside a firm
Module 2 — Market and securities manipulation
2.1 Pump and dump
2.2 Microcap and penny stock fraud
2.3 Boiler room operations
2.4 Insider tips as bait
2.5 Churning and excessive trading
2.6 What a firm can and cannot stop
Module 3 — Structural and relational fraud
3.1 Ponzi schemes
3.2 Pyramid schemes
3.3 Affinity fraud
3.4 Pig butchering and financial grooming
3.5 Recovery-room fraud
3.6 Why the same victim is approached twice
Module 4 — Fee, access and entity deception
4.1 Advance fee fraud
4.2 Prime bank and secret trading programmes
4.3 Pre-IPO and private placement scams
4.4 High-yield investment programmes
4.5 Promissory note fraud
4.6 Financial statement fraud
4.7 Advisor impersonation and cloned firms
4.8 Alternative assets: crypto and real estate
Module 5 — How the approach arrives
5.1 Cold contact: telephone, message and email
5.2 Social media, messaging and advertising
5.3 Social engineering and the trust script
5.4 Deepfakes and synthetic media
5.5 Testimonials, reviews and manufactured credibility
5.6 Urgency, exclusivity and the close
Module 6 — The vulnerable investor
6.1 Who is vulnerable, and why
6.2 Diminished capacity
6.3 Undue influence
6.4 Family, caregiver and fiduciary abuse
6.5 Isolation as a method
6.6 Reading the account of a vulnerable customer
6.7 What a firm may and may not conclude
Module 7 — Detection inside the account
7.1 What changes before money leaves
7.2 Transactional red flags
7.3 Behavioural and communication red flags
7.4 A bad decision is not a fraud
7.5 Alerting, surveillance and case selection
7.6 Building the timeline
Module 8 — Verification
8.1 Registration and licensing checks
8.2 Verifying an entity
8.3 Verifying a person
8.4 Verifying the offer and its documents
8.5 Sources the subject does not control
8.6 Cannot be verified as a finding
Module 9 — Intervention under United States rules
9.1 The regime, and how to find your own
9.2 Trusted contacts
9.3 Temporary holds
9.4 The clock on each intervention
9.5 What is available without a rule
9.6 Raising it with the customer
9.7 Acting in the hours after a loss
Module 10 — The case file and reporting
10.1 Evidence, and how fast it disappears
10.2 Writing a file that survives
10.3 Writing the suspicious activity narrative
10.4 Where else a report goes
10.5 Closing a case
10.6 When the file is challenged
Module 11 — Conduct and boundaries
11.1 What a specialist may represent and claim
11.2 Not investment advice, not a suitability assessment
11.3 Not a clinical assessment, and not an investigator
11.4 Why nobody can promise recovery
11.5 Privacy, disclosure and the limits of what may be said
11.6 Being wrong, and keeping going

Questions

What is the AGZIT Certified Investment Fraud Specialist credential?
It is an ONRIGA-accredited professional credential in investment fraud. It covers recognising when a customer is being defrauded of their own money, verifying what they are being sold from sources the seller does not control, and acting before the transfer leaves. Holders may use the designation AGZIT Certified Investment Fraud Specialist (AGZIT-CIFS).
Who is this for?
Anybody who will be the first to see that a customer is being defrauded. That includes fraud and financial crime teams, branch and contact-centre staff, relationship managers and advisers, and people in neighbouring functions such as anti-money laundering, complaints and supervision. It is also written for people moving into financial crime work, because it assumes no prior knowledge of the subject.
Do I need any qualification or experience to enrol?
No. There is no prerequisite, no minimum experience and no prior certification required. You need an AGZIT account and English at a professional reading level. A Digital Profile is not required for certifications. Enrolment is by a single payment of US$299, which covers everything: the course, the study guide, both assessments and the certificate itself.
What material is included?
A 261-page study guide covering eleven modules, which is yours to keep whether or not you sit the assessment. Every chapter ends with a worked example showing the mechanism in practice and a scenario that tests it. There are sixty-nine of each. A practice assessment is included at the same length and on the same clock as the final.
How long does it take?
About twenty hours of reading, and you can take as long as you like. There is no deadline, no schedule and no requirement to complete the material before sitting the assessment, although skipping it is a poor strategy given how the questions are written.
What is the assessment like?
One hundred multiple-choice questions in ninety minutes, with a pass mark of seventy per cent. The questions test application rather than recall: you will be given a customer, a sequence of payments and a set of facts, and asked what the firm may do and what it must record. The practice paper is drawn from a separate pool, so working it does not reveal the final.
What happens if I fail?
Two attempts are included. The practice assessment is unlimited and nothing in it counts, so most people sit it more than once before the final. If you use both without passing, another attempt can be bought for US$4, shown in your local currency at checkout, as many times as you need.
What do I get when I pass?
A certificate carrying your name, the designation, the issue date and a unique credential ID, together with a public verification page anyone can check without an account. That page is what makes it a credential rather than a claim — an employer, a recruiter or a regulator can confirm it is genuine and current without asking you.
How long is it valid, and what does renewal cost?
Two years from the date of issue. Renewal has two parts. First, a payment of US$20, shown in your local currency at checkout, which adds a further two-year term to your current expiry date — you are reminded 30, 15 and 7 days before expiry and once after, and you have 30 days after the date to renew. Second, certificate holders are expected to complete at least three continuing education activities per year during their certification period. AGZIT sends these directly — typically four to six per year — each pairing a short educational resource with a completion check, with no additional fee and no pass mark: activities are tracked as completed, not graded. The term is not an administrative formality: the schemes are stable but the delivery is not, and a 2026 statement about how investment fraud reaches people will be substantially wrong by 2028.
How much does it cost?
US$299, shown in your local currency at checkout. That is one payment and it covers everything — the 261-page study guide, the practice assessment, both attempts at the final, and the certificate issued on passing. There is nothing further to pay, and no separate certificate fee once you have passed.
Why is this credential paid when your other courses are free to study?
Because it is a substantially larger programme. Counter-Terrorist Financing and AI Governance are shorter courses whose material can be given away; this one is 261 pages across eleven modules, with sixty-nine worked examples, sixty-nine scenarios and a question bank of over four hundred. Writing it, keeping it current and maintaining the accreditation behind it costs money, and the fee is what pays for that rather than a charge for the credential at the end. You pay once, at the start, and nothing after.
Module 9 is about United States rules. Is this credential only useful in the US?
No. Ten of the eleven modules are jurisdiction-neutral: fraud schemes, how they reach people, the indicators in an account, verification, case files and professional conduct do not change at a border. Module 9 covers what a firm may lawfully do to delay or stop a payment, which is a creature of national rule, and is written against the United States regime because it is the most developed. If you practise elsewhere, read it for the structure of the problem and Chapter 9.1 explains how to establish the equivalent provisions where you work. The assessment tests that structure rather than any rule number or time period.
How is this different from a general anti-fraud or AML qualification?
Anti-money laundering asks where money came from. Payments fraud asks whether the customer authorised the instruction. This credential asks neither. It asks whether what the customer believes they are buying is real, and whether the decision is genuinely theirs — questions no existing control in most firms answers. The money is usually clean and the payment is usually authorised, which is why firms that are excellent at both still process these losses without a single alert firing.
What kind of work does this prepare me for?
Fraud investigation and financial crime roles at banks, brokerages and credit unions, and the vulnerable-customer functions that most large firms now operate. The reasoning also travels: it applies at an adviser, a fund administrator, a law firm and a regulator, all of which meet the same problem. It is not a licence and it does not authorise you to give investment advice or to assess anybody's capacity — Module 11 is explicit about where the role ends.
What am I paying for, exactly?
The full course and all eleven modules; the 261-page study guide as a PDF you keep permanently; an unlimited practice assessment; two attempts at the final assessment (further attempts US$4 each); and, on passing, an ONRIGA-accredited certificate with a credential ID and a public verification page. Renewal after two years is charged separately at US$20; letting the certification lapse is always an option, but holders who wish to keep it current are expected to complete the continuing education activities described above.
Scroll to Top